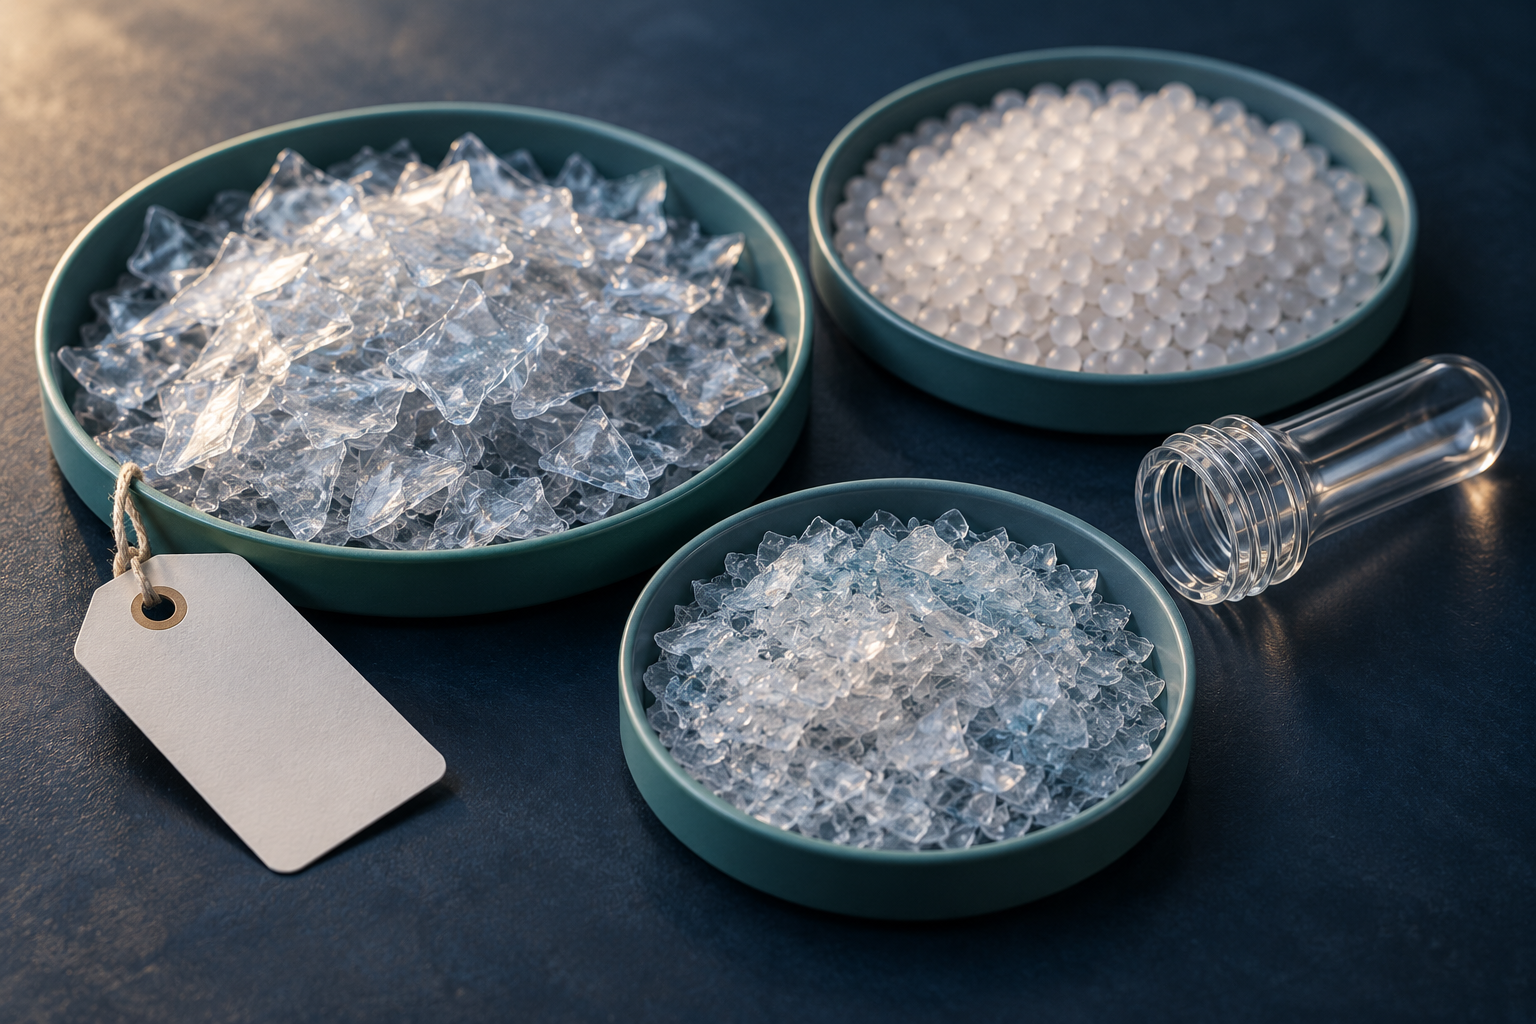
Plastic Packaging Tax is unusual among environmental measures because it does not ask you to reduce anything. It asks a single specification question about each plastic packaging component you manufacture or import: does it contain at least 30 per cent recycled plastic? If the answer is no, the component is chargeable, subject to scope, the statutory exemptions and any relief that applies. The tax does not attach to every packaging component regardless of scope, and the exclusions are part of the test rather than a footnote to it.
Who is actually in scope
The obligation sits with UK manufacturers of plastic packaging components and with businesses importing plastic packaging components, whether those components are empty or already filled with goods. A business that simply buys UK-made packaging from a UK manufacturer is generally not the taxpayer, although the cost will usually appear in the price.
There are two registration tests and both need running. You must check whether you have manufactured or imported 10 tonnes or more of finished plastic packaging components in the last 12 months, and separately whether you expect to manufacture or import 10 tonnes or more in the next 30 days. The forward looking test is the one businesses forget, and it is the one that catches a new product launch or a step change in volume.
It is worth stating plainly that the threshold counts finished plastic packaging components you manufacture or import, including components containing 30 per cent or more recycled plastic, which are not themselves chargeable. Relevant statutory exclusions apply to what counts, so check those against your own product list. Businesses regularly conclude they are below the line because most of their material already meets the recycled content test, which confuses the registration question with the payment question.
The rate applying to chargeable components from 1 April 2026 is £228.82 per tonne. Rates are revised, so confirm the current figure before using it in a model.
Source: GOV.UK, check if you need to register for Plastic Packaging Tax
Evidence is the whole exercise
The recycled content percentage is a claim about material that no longer looks like what it used to be. Nobody can inspect a finished tray and establish its provenance, which is why the regime rests on records: supplier declarations, batch level information, production data and the working that connects an input volume to a finished component.
Two practical weaknesses recur. The first is a single supplier certificate covering a product family rather than the components actually purchased, with no traceable link to delivered batches. The second is an internal calculation that nobody can reproduce, because the person who built the model has moved on and the inputs were not retained.
What good records look like
- A component level register, with weight, polymer, recycled content percentage and the basis on which that percentage is stated.
- Supplier declarations that name the component, the period they cover and the method used, with a revision date.
- Import records that identify plastic packaging components separately, including filled packaging, rather than only the goods inside.
- A reconciliation between purchased or produced volumes and the tonnage declared, retained with the return.
- A note of any component where recycled content is unknown, treated as unknown rather than quietly assumed.
Do not design around future technical detail
Published material sets out changes taking effect from 1 April 2027, including a mass balance approach for chemically recycled plastic and the treatment of pre-consumer material. If those mechanisms are central to your supply chain it is worth reading the detail early. If they are not, the sensible action today is to make your existing evidence solid rather than to build a model around rules that are not yet in force.
Source: GOV.UK, Plastic Packaging Tax: mass balance approach and removal of pre-consumer plastic
The procurement consequence
Once recycled content is a tax variable, it belongs in the specification alongside dimensions and barrier performance, with an evidence requirement attached. The question to a supplier is not whether the material is recycled. It is what percentage, measured how, evidenced by what document, and for which delivered batches.
That is a small change to a purchasing template and it removes most of the argument at year end.